
Posted on November 6, 2026
Open Table Insights: Mimicry, Blends or Back to Beans: What’s Next for Plant-Based in the Nordics?
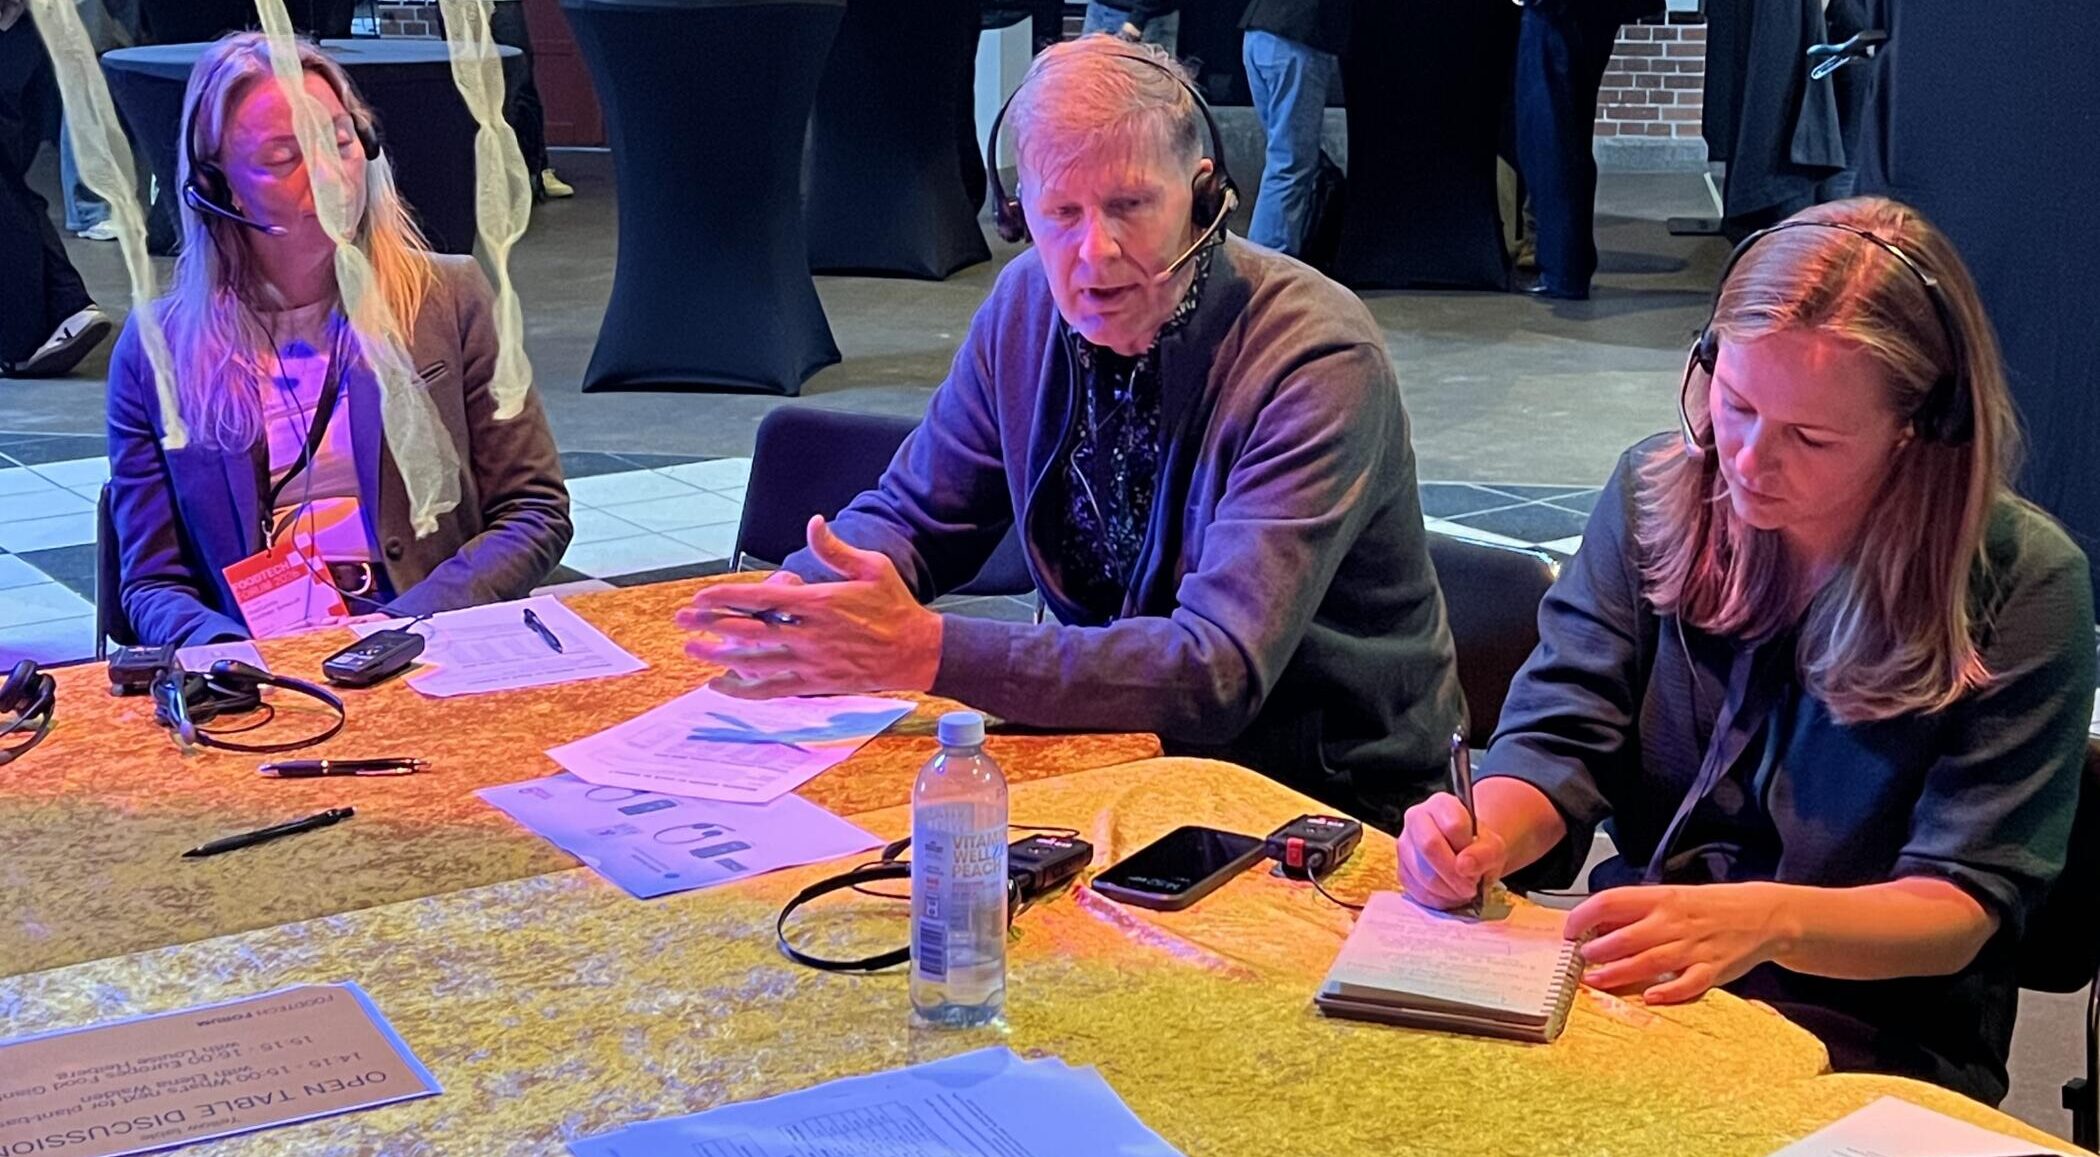
Some of the most valuable conversations at Foodtech Forum 2026 happened around the table. Through six Open Table Discussions, participants met in smaller groups to dig deeper into some of the questions shaping the future of food, from AI and circularity to scaling, investment and new business models. One conversation explored where plant-based food is heading next, from meat-mimicking products and whole foods to blended solutions. Here are some of the key insights from the discussion, led by Elena Walden, Senior Policy Manager & Research Lead at The Good Food Institute Europe.
Summary
The discussion explored the future of plant-based food in the Nordics, comparing three approaches: products that mimic meat, whole-food alternatives such as beans and tofu, and blended products that combine plant-based and animal-derived ingredients.
A central question was which approach has the greatest potential to encourage more consumers to shift towards plant-based protein while creating commercially viable business opportunities.
The discussion suggested that the plant-based market is evolving beyond the initial focus on meat alternatives. While meat-mimicking products remain relevant, investor confidence appears more cautious, and whole-food products are gaining interest among consumers seeking natural and less processed options. Blended products emerged as a particularly promising approach because they can reduce the amount of meat consumed without requiring consumers to give it up entirely.
The key takeaway was that the next phase of plant-based innovation may depend less on convincing consumers to replace meat completely and more on developing products that combine taste, nutrition, affordability and sustainability in ways that fit existing eating habits.
Three pathways for the future of plant-based food
The discussion centred on three main product categories:
- Mimicry: Plant-based products designed to replicate meat in taste, texture and functionality.
- Whole foods: Less processed plant-based foods, including beans, legumes and tofu.
- Blends: Products combining plant-based and animal-derived ingredients to balance taste, nutrition, functionality and environmental impact.
The underlying question was which category can reach the largest number of consumers, particularly those who still eat significant amounts of meat.
Participants questioned whether parts of the plant-based industry have focused too heavily on consumers who are already positive towards plant-based diets, rather than developing products that appeal to mainstream meat eaters.
Mimicry: Still relevant, but no longer the obvious growth engine
Plant-based meat alternatives have faced challenges in several European markets, and the discussion reflected a more cautious investor perspective towards the category.
One concern is whether these products have successfully reached consumers who regularly eat meat or primarily appealed to people already interested in plant-based alternatives.
At the same time, meat-mimicking products offer a relatively accessible way for consumers to try plant-based alternatives because they fit familiar eating habits and meal formats.
The discussion did not suggest that mimicry is disappearing. Rather, its role may be changing: it remains one route to introducing consumers to plant-based protein, but is no longer necessarily seen as the category’s dominant growth opportunity.
Whole foods: Growing interest, but questions about mainstream appeal
Beans, legumes, tofu and other less processed plant-based foods are attracting interest as consumers place greater emphasis on naturalness, health and simpler ingredients.
These products can offer nutritional and sustainability benefits while avoiding some of the formulation and processing challenges associated with highly engineered meat alternatives.
However, participants questioned whether this growth is concentrated among consumers who already eat relatively little meat or are particularly health-conscious.
Whole foods remain an important part of the long-term transition towards more plant-based diets, but the discussion raised the question of whether they can drive rapid, broad-based dietary change on their own.
Blends: A promising route to mainstream adoption
Blended products generated particular interest during the discussion.
Rather than attempting to replace meat entirely, these products reduce the proportion of animal-derived ingredients while retaining familiar flavours, textures and eating experiences.
Examples discussed included:
- Products combining plant protein with egg protein.
- Plant-based products incorporating animal fat or other animal-derived ingredients.
- Protein-enriched products designed to improve nutritional value without necessarily mimicking meat.
- Hybrid products that balance taste, nutrition and environmental considerations.
The appeal of blends lies in meeting consumers where they are today. Instead of asking people to make a complete dietary change, blended products offer a more gradual way to reduce meat consumption.
This approach was viewed as commercially promising because it could combine consumer familiarity with increased use of plant-based ingredients.
However, its success will depend on product quality, price, clear positioning and the ability to demonstrate meaningful benefits.
Precision fermentation and the next generation of ingredients
Precision fermentation emerged as an important technology for the future of plant-based and alternative proteins.
The technology offers opportunities to produce specific proteins and develop functional ingredients that can improve the performance of food products.
Potential applications include:
- Improving taste and flavour profiles.
- Developing ingredients with specific functional properties.
- Enhancing nutritional composition.
- Addressing some of the formulation challenges that limit the appeal of plant-based products.
These capabilities could support both plant-based and blended products, helping manufacturers develop foods that better meet consumer expectations.
The discussion pointed towards a future in which innovation may increasingly focus on the ingredients and technologies behind products, rather than only on whether a product is marketed as plant-based or animal-based.
Taste remains a critical challenge
Taste, particularly umami, was identified as an important factor influencing the success of plant-based products.
Many consumers value the savoury flavour associated with meat, and products that fail to replicate this experience can struggle to gain repeat purchases.
This makes flavour development a central innovation challenge. New ingredients, fermentation technologies and improved formulations could help manufacturers create products that are more appealing to mainstream consumers.
Ultimately, sustainability and nutritional benefits alone may not be enough to drive adoption. Products must also deliver on taste, texture, convenience and price.
Key takeaways
The discussion highlighted six important considerations for the future of plant-based food in the Nordics:
- Look beyond traditional meat alternatives: Mimicry remains relevant, but the category needs to evolve to reach a broader consumer base.
- Make whole foods more accessible and appealing: Beans, legumes and tofu have long-term potential, particularly as interest in health and less processed foods grows.
- Explore blended products: Combining plant-based and animal-derived ingredients may offer a practical route to reducing meat consumption among mainstream consumers.
- Invest in ingredient innovation: Precision fermentation and improved protein functionality could help address challenges related to taste, nutrition and product performance.
- Put taste and affordability first: Products need to meet everyday consumer expectations if they are to achieve widespread adoption.
- Focus on actual dietary change: Success should be measured not only by sales of plant-based products, but also by the extent to which innovations help reduce reliance on animal-derived ingredients.
Overall conclusion
The discussion highlighted an evolving plant-based category in which no single product format is likely to meet every consumer need.
Meat alternatives can provide a familiar entry point, whole foods offer a less processed option, and blended products may help bridge the gap between current eating habits and lower-impact diets. Meanwhile, ingredient technologies such as precision fermentation could improve the taste, functionality and nutritional profile of products across these categories.
The central question is no longer simply how to replace meat, but how to develop attractive, scalable products that help more people consume less meat without compromising on taste, convenience or affordability.